Three Cash Numbers To Keep Separate
Mortgage approval does not tell you everything you need in the bank. A Vancouver condo buyer may have enough for the down payment but still need tax, professional fees, insurance and an adjustment payment. Start with a written budget before making an offer, then replace estimates with confirmed amounts as the purchase progresses.
Deposit
Money paid on the contract's schedule and credited toward the purchase on completion. It is ordinarily part of your down payment, rather than another fee on top of it.
Down Payment
The portion of the price you fund instead of borrowing. The deposit already paid reduces the remaining amount you need to provide at completion.
Closing And Setup Costs
Taxes, fees, adjustments and move-related spending. Budget these separately so the full down payment does not consume all available cash.
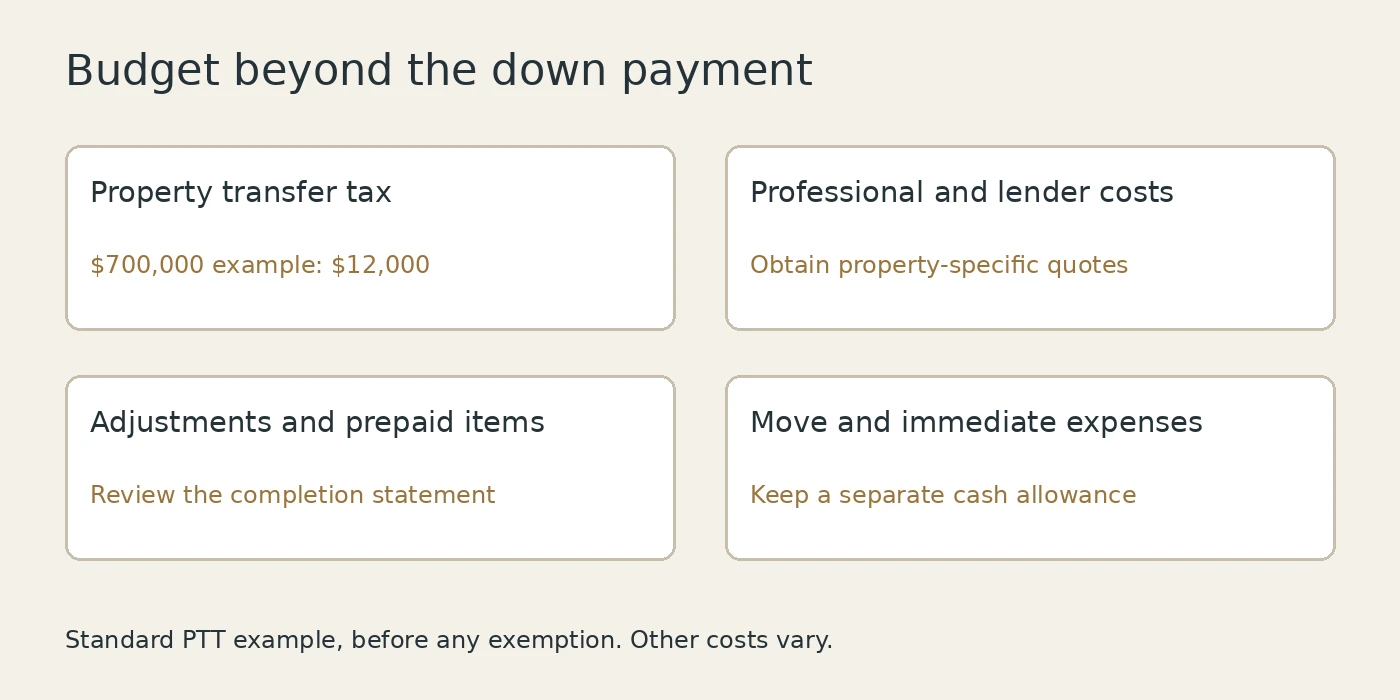
For a hypothetical $700,000 resale purchase with a chosen $140,000 down payment and $35,000 deposit, the remaining down payment is $105,000. If no PTT exemption applies, general PTT adds $12,000. That means $117,000 remains to fund those two items, before professional fees, adjustments, insurance and any other applicable costs. The down payment and deposit here are teaching assumptions, not minimum requirements or recommended amounts.
See how BC real estate deposits work for the contract and trust-account details. Do not count the same deposit twice in your cash plan.
Property Transfer Tax: Calculate The Brackets
BC's general Property Transfer Tax (PTT) is based on fair market value at registration. For an ordinary open-market purchase, the price will often reflect that value; unusual transactions require closer review. PTT is separate from the annual property-tax bill.
- 1% on the first $200,000.
- 2% on the portion above $200,000 up to $2,000,000.
- 3% on the portion above $2,000,000.
- A further 2% applies to residential value above $3,000,000, subject to applicable rules.
The examples below assume a full purchase at the stated fair market value, no exemption and no additional property transfer tax. They show PTT alone, not total closing costs.
| Purchase price / assumed value | Estimated PTT / calculation | Other costs to plan for |
|---|---|---|
| $700,000 | $12,000 $2,000 + ($500,000 × 2%) | Professional fees, inspection, insurance, adjustments, lender requirements and moving. |
| $1,000,000 | $18,000 $2,000 + ($800,000 × 2%) | The same cost categories; confirm new-home taxes if applicable. |
| $1,500,000 | $28,000 $2,000 + ($1,300,000 × 2%) | The same cost categories; leave room for completion adjustments. |
Only the amount within each bracket takes that bracket's rate. A $1,500,000 purchase is not taxed at 2% on its entire value. If an exemption applies, calculate the general tax first and then the eligible reduction.
An Exemption Is Not The Same As “No Tax”
BC First-Time Home Buyers' Program
For an entirely eligible transfer, current provincial amounts provide full general PTT relief at values of $500,000 or less. Above $500,000 through $835,000, the exemption amount is $8,000; it phases down above $835,000 and is gone at $860,000. Consequently, an eligible $700,000 purchase can still have $4,000 PTT payable: $12,000 general tax less $8,000 relief.
Eligibility includes citizenship or permanent-resident status, BC residency/tax-return criteria, first-home history, property size and principal-residence use. The provincial program does not simply use the federal definition of a first-time buyer. If only one of two purchasers qualifies, relief can be limited to that purchaser's eligible interest. Confirm all criteria and ongoing occupancy obligations before counting on the saving.
BC Newly Built Home Exemption
A qualifying newly built principal residence can receive full PTT relief through $1,100,000, with partial relief above that amount and below $1,150,000. It is not restricted to first-time buyers. The home's qualifying status, purchaser status, land area and occupancy requirements still matter. A “new-looking” renovated resale is not automatically a qualifying newly built home.
For a qualifying $1,000,000 new home, the general $18,000 PTT could therefore be eliminated. That does not eliminate GST, legal costs or the other completion items. Compare presale and resale purchases using their complete tax and timing picture.
GST: Typical Resale Versus New Construction
Sales of used residential housing are generally GST-exempt. A new or substantially renovated home may be taxable, and unusual use or ownership circumstances can change the answer. Confirm the contract's tax clause instead of assuming every resale is exempt or every advertised price includes GST.
For illustration, a taxable $1,000,000 price stated before 5% GST adds $50,000 before any rebate. Ask whether the price includes tax, whether a rebate is credited by the builder and whether you must fund the tax first and claim later.
A provincial PTT exemption and federal GST rebate address different taxes. Qualifying for one does not establish eligibility for the other. Other exemptions and the existing new-housing rebate may be relevant to particular purchases; ask for a written, transaction-specific calculation.
Build A Costs Worksheet, Not A Universal Percentage
There is no single closing-cost percentage that works equally well for an exempt resale condo and a taxable new home. Use these categories to request actual quotes. No fixed legal, inspection or insurance price is assumed here.
| Item | What to confirm | When to plan for it |
|---|---|---|
| Lawyer or notary | Professional fee, taxes, registration, searches and other disbursements. Ask what the quote includes and what creates extra work. | Choose early; funds required before completion. |
| Home inspection | Scope, access, condo versus house coverage and specialist reviews. A unit inspection does not replace strata-document or envelope review. | Usually during due diligence, if provided for. |
| Appraisal and lender costs | Whether an appraisal is needed, who pays, fees deducted from mortgage proceeds and any bridge-financing cost. | Before financing is finalized. |
| Title insurance | Whether required or recommended, policy coverage and premium. It is distinct from home insurance. | With the conveyancer and lender. |
| Home / condo insurance | Coverage effective when required by the contract/lender. For condos, review improvements, liability and strata-deductible exposure. | Arrange before completion. |
| Adjustments | Taxes, strata fees and applicable prepaid services. Get the estimated statement and understand credits as well as charges. | Before final funds are delivered. |
| Strata move and document costs | Move-in fees, elevator booking, refundable damage deposits, keys/fobs and relevant document charges. Confirm payer under the contract. | Before booking the move. |
| Moving and setup | Movers, parking/access, utility accounts, cleaning, locks and immediate essentials. Separate optional improvements. | Possession and the first weeks. |
Ask the lender to distinguish the mortgage amount from the net funds advanced. A financed mortgage-insurance premium or deducted fee affects the borrowing picture differently from an expense you pay separately. Avoid assuming the lender will advance money for closing costs.
For a Vancouver strata purchase, read the bylaws and move procedures before booking a large truck. A refundable elevator deposit is a temporary cash requirement; a non-refundable move fee is an expense. Both may require money before moving day, but they belong in different lines of the worksheet. Review approved levy instalments separately from ordinary monthly-fee adjustments.
Why The Statement Of Adjustments Changes The Cash Total
Adjustments allocate applicable expenses between seller and buyer as of the contract's adjustment date. Completion, possession and adjustment dates can differ. If the seller has prepaid an item for a period benefiting the buyer, the buyer may reimburse that share. If an amount remains unpaid, the arrangement may instead create a credit or require payment on completion.
Hypothetical property-tax illustration: assume $3,650 covers a 365-day year and has already been paid by the seller. If the buyer's allocated portion is 100 days, the simple reimbursement is $3,650 ÷ 365 × 100 = $1,000. This demonstrates prorating, not an actual Vancouver tax bill or a direction about which dates to include. The conveyancer confirms the tax notice, grants, payments and contractual allocation.
Monthly strata fees can be adjusted similarly. Utility or service adjustments depend on billing and the contract; many accounts are simply closed and opened by the respective owners. Avoid putting every utility into a presumed adjustment. Ask why each line is there, what period it covers and whether it is a debit or credit.
When The Money Is Needed
- Offer acceptedReview dates, tax treatment and the overall cash plan.
- Subjects / due diligencePay for agreed inspections and confirm financing, documents and insurance.
- DepositDeliver on the contract schedule. It may be due at a different point from this example.
- Legal / notary workConfirm identity, lender instructions, tax eligibility and the estimated statement.
- Completion costsProvide cleared funds by the conveyancer's deadline so title and financing can complete.
- PossessionMove under the contract arrangements; retain funds for setup and immediate needs.
Do not leave a large withdrawal or investment sale to the last day. Confirm transfer limits and clearing times with your financial institution and conveyancer. Independently verify payment instructions using an established contact method, especially if an unexpected email changes banking details.
Before You Remove Subjects, Check These Six Items
- A tax estimate with the exemption assumptions explicitly recorded.
- Written mortgage terms and the expected net advance.
- Quotes for professional work and required inspections.
- Insurance availability and the date coverage must begin.
- Strata fees, levy dates and move requirements where applicable.
- A liquid cash reserve for adjustments, moving and ownership after completion.
Questions Buyers Ask About Completion Funds
Is my deposit an extra closing cost?
No. It is normally credited toward the price on completion and forms part of your down payment. It still has its own contractual deadline.
Does a first-time buyer pay no PTT on a $700,000 home?
Not automatically. If the entire transfer qualifies under the current BC first-time buyer program, $12,000 general PTT less the $8,000 exemption leaves $4,000 payable.
Can I use a GST rebate to reduce cash due on completion?
Only if the actual transaction arrangements permit it. Confirm eligibility and whether the builder credits the rebate or you must pay first and claim later.
Why is the final amount different from my first estimate?
Actual adjustments, net mortgage proceeds, taxes and disbursements can differ from planning assumptions. Ask for the itemized statement and reconcile amounts already paid.
Sources And Program Details
Tax information reviewed October 3, 2026. Hypothetical amounts illustrate the calculations; provider costs require current quotes.
Planning A Purchase?
If you would like help organizing the purchase timeline and the questions to take to your lender and conveyancer, contact Spencer.